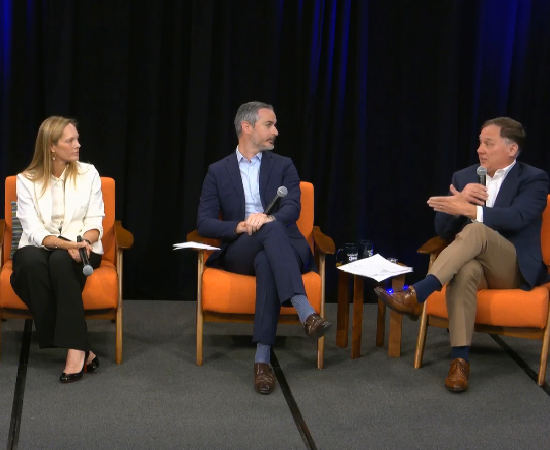
Estate planning is about more than passing along assets. It's about protecting the people you care about, preparing for life's uncertainties, and helping ensure your wishes are carried out. During a live discussion hosted by Cascade PBS, Washington Trust wealth management professionals shared practical guidance on estate planning, taxes, investment management, and the role of professional fiduciaries.
Video Quick Guide
A full recording of the discussion is available at the end of this article. Curious about a specific estate planning topic? Below is a breakdown of the topics discussed, including a brief summary. Want all the details? Select the hyperlinked timestamp and you'll be taken to that portion of conversation.
What an Estate Plan Includes and Why It Matters (12:12)
Many people think estate planning begins and ends with a will, but a comprehensive estate plan often includes much more.
Trusts, powers of attorney, health care directives, beneficiary designations, and other legal documents work together to communicate a person's wishes and provide instructions if they become incapacitated or pass away.
A thoughtfully designed plan can help protect loved ones, direct assets according to personal goals, and ensure important decisions remain in the hands of trusted individuals rather than defaulting to state law.
Washington and Federal Estate Tax Considerations (17:14)
Estate taxes can be a surprise for many families, particularly because Washington has its own estate tax system that differs from federal estate tax rules.
It’s important to know how estate values are calculated, the role of deductions and exemptions, and how gifts made during a person's lifetime may influence estate-planning strategies.
Learning about these rules early can help families make more confident decisions and avoid surprises later.
Planning Investments for Uncertain Markets (21:48)
Market volatility is a normal part of investing, but that does not mean investors should abandon their long-term plans when uncertainty arises.
A diversified portfolio can help support your goals while managing risk through changing market conditions.
By focusing on a strong investment foundation, maintaining proper asset allocation, and periodically rebalancing portfolios, investors can better position themselves to navigate changing market conditions without losing sight of their long-term objectives.
The Responsibilities of a Fiduciary (26:02)
Serving as a trustee or personal representative involves far more responsibility than many people realize.
Fiduciaries may be responsible for managing investments, overseeing trust administration, handling taxes and recordkeeping, communicating with beneficiaries, and coordinating with legal and financial professionals.
These duties require significant time, expertise, and attention to detail, which is why choosing the right individual or institution is an important estate-planning decision.
When to Consider a Professional Trustee (29:37)
While many people naturally think of naming a family member as trustee, there are situations where a professional fiduciary may be a better choice.
Professional trustees bring experience, objectivity, and continuity to the administration process while helping families navigate complex financial and legal responsibilities.
In some cases, appointing a neutral third party can also reduce family tension by allowing relatives to focus on their personal relationships rather than the administrative demands of managing an estate or trust.
Preparing to Meet with an Estate Planning Attorney (35:41)
A very practical and tangible first step is preparing for an initial meeting with an estate-planning attorney.
It’s recommended starting with three key questions: What do you own? Who should receive your assets? And who should serve in important decision-making roles if something happens to you?
Entering a planning process with a general understanding of your assets, intentions, and trusted decision-makers can make conversations more productive and help create a plan that aligns with your goals.
Coordinating Titles and Beneficiary Designations (37:09)
Even the most carefully drafted estate plan can be undermined if account ownership and beneficiary designations are not consistent with the overall plan.
Retirement accounts, life insurance policies, and jointly owned property may transfer according to beneficiary forms or ownership structures rather than instructions contained in a will.
Periodically reviewing these details helps ensure assets pass according to your intentions and prevents unexpected outcomes for heirs.
When to Update an Estate Plan (40:38)
Estate planning is not a one-time event. Life changes such as marriage, divorce, births, deaths, retirement, relocations, and shifts in financial circumstances can all affect the effectiveness of an existing plan.
Individuals are encouraged to review their documents periodically and revisit key decisions about trustees, personal representatives, and beneficiaries as circumstances evolve. Regular updates help ensure estate plans continue to reflect current wishes and family needs.
Connecting Retirement, Investment and Estate Planning (42:36)
There’s a close relationship between retirement planning, investment management, and estate planning. Decisions made today about saving, investing, and spending can influence not only retirement security but also the legacy individuals hope to leave behind.
Financial planning is an ongoing process that should evolve alongside changing goals, family circumstances, and market conditions.
When these elements are viewed together rather than separately, families are often better positioned to achieve both their lifetime and legacy objectives.
A Coordinated Strategy
Successful planning is not just about documents or investments. It is about creating a coordinated strategy that reflects your values, protects those you care about, and adapts as life changes. Whether you are developing your first estate plan or revisiting an existing one, taking the time to understand these topics can help create greater confidence for both you and your family.